Early Retirement Income Before 59 1/2: What to Spend First and What to Avoid
PenaltyFreeRetire Editorial ·
Federal law checked Sep 20, 2026 · Covers 2026 rules · Next review Nov 30, 2026
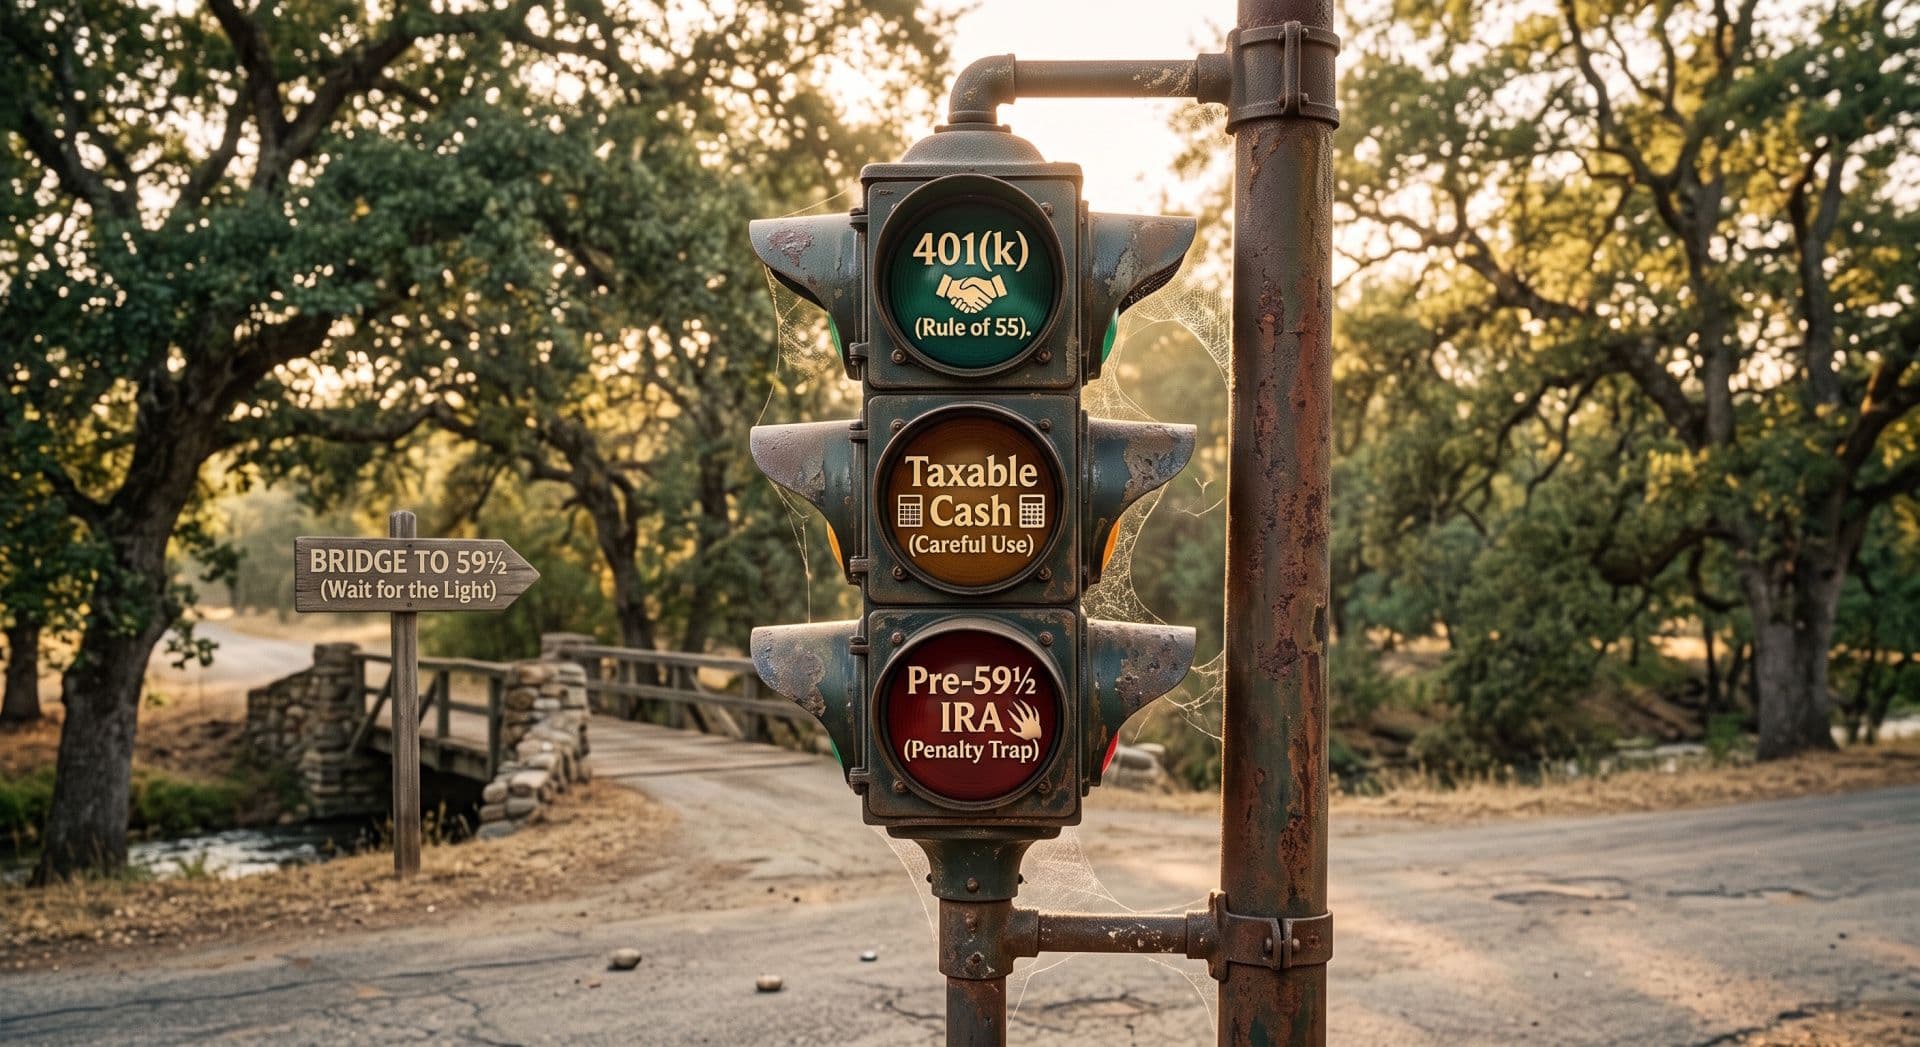
Early retirement income before 59½ usually comes from several accounts rather than one magic bucket. The first question is whether the Rule of 55 applies, which depends on when you separated from service, which plan holds the money, and what that plan allows. If it does apply, the 401(k) at the employer you left may be the cleanest bridge. If it does not, many people move next to taxable cash, Roth contribution basis and older conversions, and only then to more rigid options. The sources described here are common ones rather than a complete list.
The expensive mistakes are rarely about running out of money on paper. They come from pulling the wrong dollars in the wrong order. A $60,000 spending year funded from a brokerage account does not always create $60,000 of taxable income. A $60,000 withdrawal from a pre-tax 401(k) or IRA usually does. If you are buying Marketplace health insurance before Medicare, that income difference can also change your premium tax credits.
TL;DR: Start by checking Rule of 55 eligibility. It requires separating from service during or after the calendar year you turn 55, and the distributions must come from the qualified employer plan tied to that separation, subject to that plan's own terms. If that door is open, it can work better than a Roth ladder for the first bridge years because there is no five-year wait and no fixed payment schedule. If it is closed, taxable assets often give you the most control, Roth dollars help only if the ordering and five-year rules work in your favor, and SEPP 72(t) is a fallback when easier options are not enough. The Rule of 55 Calculator is a simplified planning illustration based on what you enter rather than individualized advice, and Why the First Five Years of Early Retirement Can Make or Break Your Roth Ladder is worth keeping nearby if you need a longer bridge.
Start with the one rule that can simplify everything
IRS Publication 575 describes an exception to the 10% early distribution tax for distributions from a qualified retirement plan after you separate from service during or after the calendar year you reach age 55. The distribution has to come from the qualified employer plan tied to that separation, and the plan's own terms control which withdrawals are actually available. Qualified public safety employees, including private-sector firefighters, may qualify under an earlier threshold of age 50 or 25 years of service where that applies.
Two details are critical:
- The exception is tied to the qualified employer plan connected to the separation that happened during or after the year you turned 55, not to every retirement account you own. Each employer plan is evaluated separately, so a balance left behind at an earlier employer does not qualify.
- If you roll that plan into an IRA before taking the bridge withdrawals, you generally lose the Rule of 55 route, and even when you keep the plan, its terms still control how much you can take and how often.
That is why this question comes first. If the Rule of 55 is available, you may not need to touch taxable assets as aggressively, start a SEPP, or rush into a Roth ladder just to cover the next few years. Governmental 457(b) plans work differently. Distributions from a governmental 457(b) after separation from service are generally not subject to the 10% early distribution tax at all, although amounts rolled into the plan from other plan types can keep their own rules.
Run the Rule of 55 Calculator before you move the account anywhere, and treat the result as a simplified illustration to confirm against your plan documents. If the exception appears to apply, protecting that option first is usually worth more than optimizing around it.
The usual order of operations before 59½
There is no universal withdrawal order, and the sources listed below are not exhaustive, but there is a common pattern that keeps showing up in solid early retirement plans.
1. Taxable cash and brokerage assets
Taxable money is usually the most flexible bridge asset. You can choose which lots to sell, harvest gains or losses, and in many cases spend cash that is not fully taxable because part of the sale is just your cost basis coming back to you.
That does not mean taxable is always cheap. Dividends, interest, and realized capital gains still matter. But it often gives you more control over reported income than pre-tax retirement accounts do.
2. Rule of 55 withdrawals, if you qualify
If you separated from service during or after the calendar year you turned 55, the qualified employer plan tied to that separation can be a clean source of bridge income, provided the plan allows the withdrawals you need. You avoid the 10% early distribution tax, you are not locked into fixed annual distributions, and many plans let you take only what you actually need. Some plans limit you to a lump sum or a small number of withdrawals, so the plan document decides what is possible.
This is where many people make a bad rollover too early and lose the easiest option on the board.
3. Roth IRA contributions and older conversion basis
IRS Publication 590-B says Roth IRA distributions follow an ordering rule. Regular contributions come out first. After that, conversions and rollovers come out on a first-in, first-out basis. Each conversion has its own five-year clock for the 10% additional tax if you are still under 59½.
In plain English, direct Roth contributions are usually the easiest Roth dollars to reach. Converted dollars can work too, but only if enough time has passed on that specific conversion.
4. New Roth ladder planning
A Roth ladder is a great long-game tool, but it does not solve this year by itself. The conversion you do today is mainly building income for five calendar years from now. That is why a taxable bridge matters so much for people retiring well before 59½.
If you need help sizing those conversions, The Roth Conversion Sweet Spot is the companion piece to keep open.
5. SEPP 72(t) when the simpler options are not enough
SEPP is real and useful, but unfortunately easy to misuse. Notice 2022-6 and the current IRS SEPP guidance make the tradeoff clear: if you start substantially equal periodic payments, you generally have to keep them going until the later of five years or age 59½. That can save the penalty, but it also removes flexibility.
For someone who just needs a short bridge and has other choices, SEPP is often the last tool to reach for, not the first.
Why taxes can get ugly even when the penalty is avoided
The 10% early withdrawal penalty gets most of the attention, but it is not the whole problem.
What matters in bridge years is the tax character of the dollars you spend.
- Rule of 55 withdrawals and most traditional IRA withdrawals are generally taxed as ordinary income.
- Selling from a taxable account can produce much less taxable income than cash spent because part of the sale may be your original basis.
- Qualified dividends and long-term gains may be taxed at lower rates than ordinary income, but they still count in the income picture.
- Roth conversions add ordinary income in the year of the conversion even though you are moving money to a better tax bucket later.
This becomes more important if you are on ACA Marketplace coverage before 65. HealthCare.gov bases Marketplace savings on expected household income for the coverage year, and the IRS Form 8962 instructions say changes in income should be reported to the Marketplace during the year. For 2026 coverage, premium tax credit eligibility generally ends above 400% of the federal poverty level, and the applicable percentage that sets your expected contribution reaches 9.96% of household income in the 300% to 400% range. After 2025, excess advance premium tax credits no longer have the old household-income repayment cap, so an income surprise can mean repaying the full excess at tax time. A bridge-year Roth conversion or a large realization of gains can therefore affect much more than your tax bracket.
The key point is simple: gross withdrawals are not the same thing as taxable income. Early retirees who miss that point often pay more tax than they needed to.
Three bridge-year setups that come up all the time
You are 56 and the employer plan is still intact
This is the cleanest setup. If you separated from service during or after the calendar year you turned 55, the money is still in that employer plan, and the plan allows the withdrawals you need, the Rule of 55 can cover the gap with less friction than a new SEPP and less waiting than a Roth ladder. The planning work then shifts from penalty avoidance to withdrawal sizing and tax control.
You retired earlier and built a taxable bridge on purpose
This is the classic Roth ladder setup. Taxable assets cover current spending. Roth conversions are sized to fit the tax year. Five years later, those earlier conversions start becoming available. This can work very well, but only if the bridge was funded before retirement and the conversion amounts are not chosen from the tax bracket alone. If ACA coverage is in the picture, Can a Roth Conversion Raise Your ACA Premiums? How to Plan the Subsidy Tradeoff Before Medicare should be part of the same decision.
You retired too early with most of the money in IRAs
This is the hard one. If Rule of 55 is unavailable and the taxable bridge is thin, the remaining choices get less forgiving. A partial SEPP on one IRA may help. Part-time income may help more than you expect. So can delaying full retirement for another year or two. The worst move is usually pretending the flexibility exists when it does not.
The mistakes that usually do the damage
Rolling the wrong 401(k) into an IRA
This is the big one. If the Rule of 55 is the best path, protect it before you chase lower fees or simpler account consolidation.
Assuming cash spent equals taxable income
It does not. A brokerage withdrawal, a Roth contribution withdrawal, and a pre-tax plan withdrawal can all fund the same grocery bill and create very different tax results.
Starting a SEPP on more money than you need
SEPP rules are rigid enough already. Locking the whole IRA into that schedule can create a problem you did not have to create.
Filling a tax bracket without checking health insurance
For households on Marketplace coverage, the next conversion dollar may raise federal tax and change premium tax credits at the same time. For 2026 coverage, eligibility for the credit generally ends above 400% of the federal poverty level, so the cost of one extra dollar of income can be far larger than the marginal tax rate alone suggests. That math needs one model rather than two separate guesses.
Treating the first bridge year like the only bridge year
The right answer in year one can create a bad year three if it drains taxable assets too fast or leaves no room for future conversions.
What to do before you take the first dollar
- List every account that can fund spending before 59½ and mark whether each source creates ordinary income, capital gains, or no current tax.
- Test Rule of 55 eligibility before moving any 401(k) money, including the year you separated, which plan holds the balance, and what the plan document allows.
- Separate spending needs from taxable income estimates. They are related, but they are not the same number.
- If you are planning Roth conversions, run them with the Roth Conversion Ladder Calculator and read Why the First Five Years of Early Retirement Can Make or Break Your Roth Ladder.
- If you are on Marketplace coverage, check the income effect before you finalize the withdrawal mix for the year.
FAQ
Can I use the Rule of 55 after I roll the 401(k) to an IRA?
Usually no. The exception applies to distributions from the qualified employer plan you separated from during or after the calendar year you turned 55. Once the money moves to an IRA, that route is generally gone and IRA distribution rules apply instead.
Can I spend Roth IRA contributions before 59½?
Usually yes. Under the Roth IRA ordering rules in IRS Publication 590-B, regular contributions come out first. That is different from converted amounts, which can still have a five-year issue if you are under 59½.
Is SEPP 72(t) a good short bridge tool?
Sometimes, but it is usually the fallback. Once started, SEPP generally has to continue until the later of five years or age 59½. That is a high price to pay if a taxable bridge or Rule of 55 withdrawal would have solved the same problem more cleanly.
If I sell $60,000 from my brokerage account, is $60,000 taxable income?
No. The taxable part is generally the gain, plus any dividends and interest for the year. Your original basis is not taxed again.
Why do ACA premiums belong in this conversation?
Because Marketplace savings depend on household income for the coverage year. For 2026 coverage, premium tax credit eligibility generally ends above 400% of the federal poverty level, and after 2025 excess advance credits no longer have the old household-income repayment cap. A bridge-year Roth conversion or large capital gain can change that income figure even if it looked fine from a tax-bracket view alone.
Bottom line
Early retirement income before 59½ is usually about sequence, not just savings. Check Rule of 55 eligibility first, including the year you separated, the plan tied to that separation, and what its terms allow. Use taxable assets with intent. Use Roth dollars when the ordering rules and clocks work in your favor. Treat SEPP like a backup plan that earns its way in. The right order depends on your marginal rate, your health coverage, your liquidity, and your own circumstances, so no single sequence fits every household.
If you want a quick starting point, run the Rule of 55 Calculator. It is a simplified planning illustration based on the assumptions you enter, not individualized advice or an exact tax result. Then map the rest of the bridge around the income tax you will actually report, not just the cash you plan to spend.
Sources
- IRS, Publication 575, Pension and Annuity Income
- IRS, Publication 590-B, Distributions from Individual Retirement Arrangements (IRAs)
- IRS, Notice 2022-6, Determination of Substantially Equal Periodic Payments
- IRS, Retirement topics: Exceptions to tax on early distributions
- IRS, Questions and answers on the Premium Tax Credit
- HealthCare.gov, What’s included as income
- IRS, Revenue Procedure 2025-25: 2026 Applicable Percentage Table for the Premium Tax Credit
Official sources used for this article
Free email guide
Want the one-page Roth conversion version?
Get the cheat sheet by email. It covers bracket room, the 5-year wait, and the mistakes that tend to cost the most.
- How to estimate your bracket room before you convert
- What the 5-year rule actually means in practice
- The mistakes that quietly add tax, penalties, or bad timing
We store your email and optional first name in Supabase to send the guide and record your choices. Resend delivers the email. If you do not opt into updates, we delete the record 90 days after your most recent guide request. See our Privacy Policy. Educational only. Not tax or investment advice.
Try the calculator
Put this strategy into numbers with our free Rule of 55 calculator.
Open Rule of 55 Calculator →Related Articles
Don't Roll Over That 401(k): The Early Retirement Mistake That Costs Thousands
Standard advice says roll your 401(k) into an IRA. For early retirees that can be an expensive reflex, since the Rule of 55 reaches the plan tied to your separation and an IRA distribution does not qualify. Whether rolling makes sense depends on your dates and your plan's terms.
Rule of 55 vs. 72(t) SEPP: Which Early Retirement Strategy Is Right for You?
Rule of 55 and SEPP 72(t) are two ways to reach retirement money before 59½ without the 10% additional tax, and they are not the only ones. Which one fits depends on your separation date, where the money sits, what your plan allows, and whether another statutory exception covers your situation.
The Rule of 55 Explained: Tap Your 401(k) Early Without the 10% Penalty
The Rule of 55 lets some early retirees take money from a former employer's plan before 59½ without the extra 10% tax. It is narrower than it sounds. Eligibility turns on when you separated from service, which plan the money sits in, and what your plan actually allows.