Latest from the Blog
In-depth guides on early retirement strategies, tax-efficient withdrawals, and making the most of your retirement accounts. Start with the calculators for Roth conversions, HSA planning, and Rule of 55 withdrawals, then use the articles below for the detail and tradeoffs.
Can You Still Afford to Retire Before 65 in 2027?
Yes, retiring before 65 can still work in 2027. But you cannot have the health insurance part of the plan be a rough monthly guess. You need a local premium quote, an estimate of your 2027 Marketplace income, and enough room for deductibles and other costs before Medicare begins.
PenaltyFreeRetire Editorial · October 11, 2026
Should You Delay Social Security to Create More Roth Conversion Room?
Sometimes yes. Delaying Social Security can give you cleaner low-income years to move money from a traditional IRA to a Roth IRA. But that only helps if you already have a workable bridge for spending.
PenaltyFreeRetire Editorial · August 11, 2026
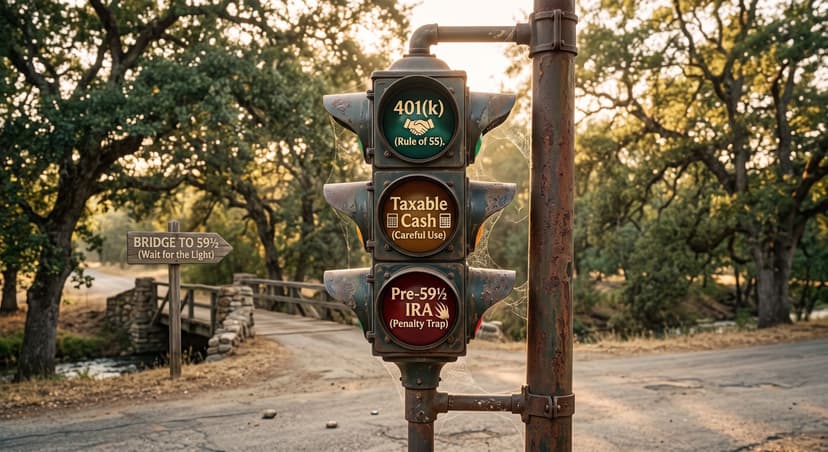
Early Retirement Income Before 59 1/2: What to Spend First and What to Avoid
Early retirement income before 59½ usually comes from several accounts rather than one bucket. The first question is whether the Rule of 55 applies, which depends on the year you separated, the plan tied to that separation, and its terms. If it does not, many people move next to taxable cash.
PenaltyFreeRetire Editorial · July 28, 2026
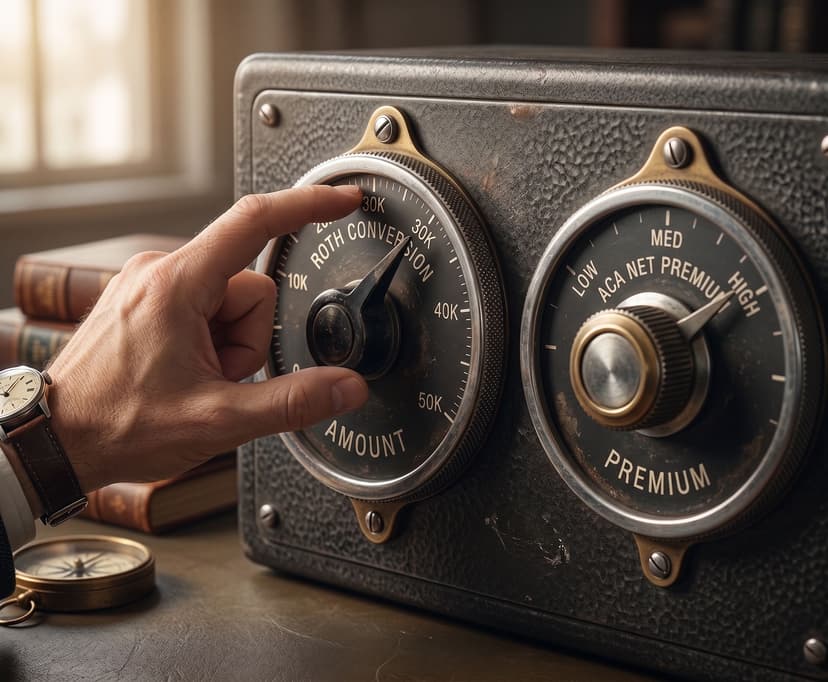
Can a Roth Conversion Raise Your ACA Premiums? How to Plan the Subsidy Tradeoff Before Medicare
Yes. A Roth conversion can raise your health insurance cost before Medicare. The reason is simple: the taxable part of the conversion increases your income for the year, and Marketplace savings are based on household income. That means the next conversion dollar can do two things...
PenaltyFreeRetire Editorial · July 6, 2026
HSA vs FSA: Which Account Actually Wins in Retirement?
Most people in their 50s treat the annual benefits enrollment period as a chore. You check the boxes, keep the same health plan you had last year, and try to remember if you spent all the money in your Flexible Spending Account (FSA) before the deadline.
PenaltyFreeRetire Editorial · May 24, 2026
What Are Required Minimum Distributions — and How to Delay or Reduce Them
Required minimum distributions generally begin at 73 for people born in 1951 through 1959 and at 75 for people born in 1960 or later. Here is how RMDs work, why they can raise taxes and Medicare costs, and what you can still do before they start.
PenaltyFreeRetire Editorial · May 17, 2026
Roth IRA vs Traditional IRA: the decision that could cost (or save) you thousands
The Roth Conversion Ladder Planner runs the year-by-year tax math on your age, balance and income, showing where each conversion lands in the brackets. It is a simplified comparison tool, not a full tax return: no state taxes, no complete RMD picture, no estate planning.
PenaltyFreeRetire Editorial · May 9, 2026
What Happens to Your HSA at 65 — and Why It Changes Everything
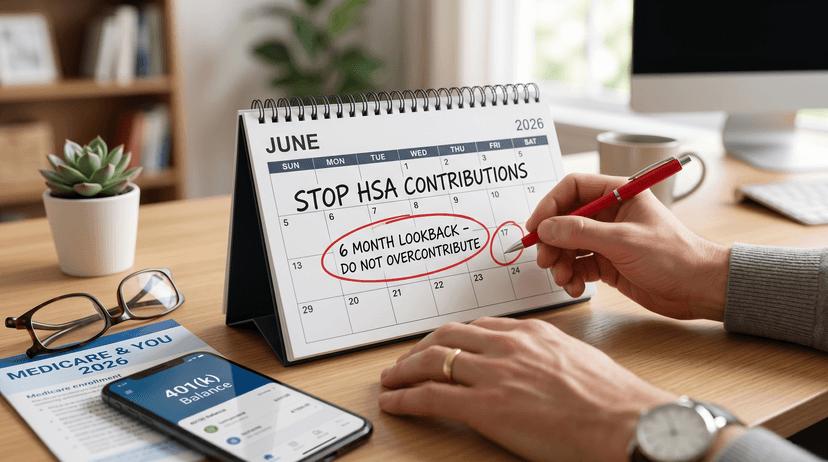
Most people stop paying attention to their HSA around the time they retire. At 65 the rules shift in your favor and the account gets more flexible. The same birthday brings a Medicare timing problem that can turn recent contributions into excess ones, so the details matter.
PenaltyFreeRetire Editorial · May 2, 2026
Roth Conversion vs. Roth Contribution: Which Strategy Wins If Tax Rates Rise?
Contribute or convert? Contributions are capped by annual IRS limits and eligibility rules, while conversions have no cap. Which fits depends on your marginal rate today versus the one you expect later, whether you can contribute or deduct, and if you have outside cash to pay the tax.
PenaltyFreeRetire Editorial · May 2, 2026
Don't Roll Over That 401(k): The Early Retirement Mistake That Costs Thousands
Standard advice says roll your 401(k) into an IRA. For early retirees that can be an expensive reflex, since the Rule of 55 reaches the plan tied to your separation and an IRA distribution does not qualify. Whether rolling makes sense depends on your dates and your plan's terms.
PenaltyFreeRetire Editorial · May 2, 2026
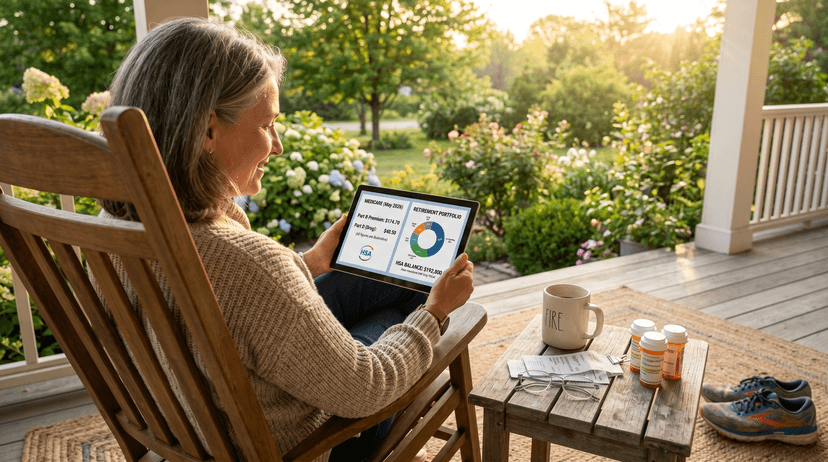
Pay Now or Invest? When to Actually Spend Your HSA
Paying medical bills out of pocket and leaving the HSA invested can grow the balance over decades. That is a simplified illustration based on assumptions, not a guarantee. It works only if you have the cash flow to cover bills today and will keep records for years.
PenaltyFreeRetire Editorial · May 2, 2026
Rule of 55 vs. 72(t) SEPP: Which Early Retirement Strategy Is Right for You?
Rule of 55 and SEPP 72(t) are two ways to reach retirement money before 59½ without the 10% additional tax, and they are not the only ones. Which one fits depends on your separation date, where the money sits, what your plan allows, and whether another statutory exception covers your situation.
PenaltyFreeRetire Editorial · May 2, 2026
The Rule of 55 Explained: Tap Your 401(k) Early Without the 10% Penalty
The Rule of 55 lets some early retirees take money from a former employer's plan before 59½ without the extra 10% tax. It is narrower than it sounds. Eligibility turns on when you separated from service, which plan the money sits in, and what your plan actually allows.
PenaltyFreeRetire Editorial · May 1, 2026
The HSA Stealth IRA: Why Your Health Savings Account Is the Best Retirement Account You're Ignoring
Most people treat their HSA like a medical debit card. Money goes in, receipts get paid, the balance stays near zero. An HSA can pair an upfront tax break with tax-free growth and tax-free withdrawals for qualified medical costs, which makes it worth treating as a long-term account.
PenaltyFreeRetire Editorial · May 1, 2026
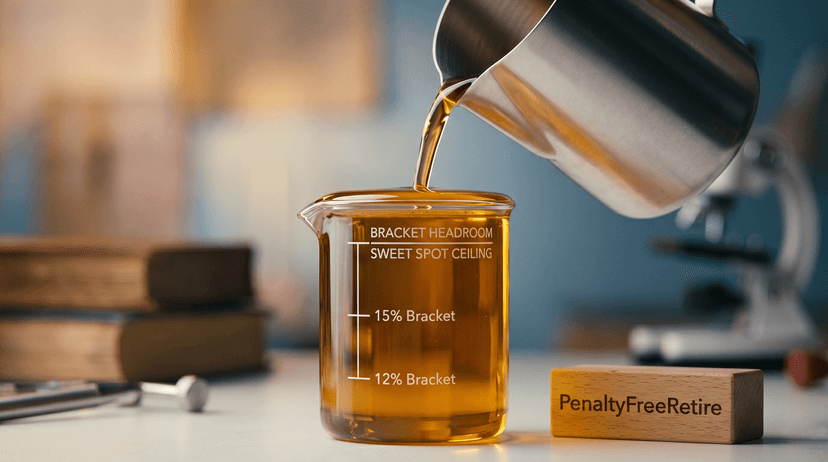
The Roth Conversion Sweet Spot: How to Find Your Optimal Annual Conversion Amount
How much to convert may depend on your bracket headroom, the gap between your taxable income and the top of your current bracket, along with your wider tax picture. The PenaltyFreeRetire Roth Conversion Ladder calculator gives a simplified federal projection as a starting point.
PenaltyFreeRetire Editorial · May 1, 2026
Why the First Five Years of Early Retirement Can Make or Break Your Roth Ladder
Roth distributions come out in order: contributions first, then conversions oldest first, then earnings. Each conversion has its own five-tax-year clock for the 10% early distribution tax, so your first conversion can't fund year one of retirement without a bridge.
PenaltyFreeRetire Editorial · May 1, 2026
Popular calculators to pair with these guides
These calculator pages now have more direct internal paths from the blog, which should also help reinforce the site structure for search.
Compare All Retirement Calculators
Choose the calculator that best matches your early-retirement withdrawal strategy.
Roth Conversion Ladder Calculator
Model annual conversions, five-year access windows, and tax-aware bridge income.
HSA Triple Tax Advantage Calculator
Project the long-term value of maxing out an HSA before and during retirement.
Rule of 55 Calculator
Check whether employer-plan withdrawals can cover the gap before age 59 1/2.
Early Retirement Blog
Read practical guides on IRS rules, withdrawal sequencing, and retirement tax strategy.