The Roth Conversion Sweet Spot: How to Find Your Optimal Annual Conversion Amount
PenaltyFreeRetire Editorial ·
Federal law checked Sep 20, 2026 · Covers 2026 rules · Next review Nov 30, 2026
Most people who look at a Roth Conversion Ladder worry about the same two risks. Convert too much in a single year and part of the money gets taxed at a higher rate than it needed to be. Convert too little and you may leave years of tax-free growth unused. The middle ground, often called bracket fill, is where most of the planning happens. The idea is simple. You top off your current tax bracket without pushing income into the next one. Every dollar you convert inside your bracket is taxed at the same rate, and only the dollars that cross the line are taxed at the higher rate above it. Whether that trade is worth making depends on your full tax picture and on what you expect tax rates to look like later.
TL;DR: A common starting point is the gap between your taxable income and the top of your current tax bracket, sometimes called bracket headroom. The PenaltyFreeRetire Roth Conversion Ladder calculator gives you a simplified federal projection of that gap. What actually makes sense for you depends on the rest of your return and on your assumptions about future tax rates.
What Is a Roth Conversion Ladder?
A Roth Conversion Ladder is one way early retirees turn retirement-account money into accessible cash without triggering the usual 10% early withdrawal penalty.
Here is how it works. You move money from a Traditional IRA or 401(k) into a Roth IRA. You pay ordinary income tax on the converted amount in the year you move it. Then you wait five years. After that waiting period, you can withdraw the converted principal (the amount you moved, not the earnings on it) without the early withdrawal penalty. Earnings generally stay in the Roth until you reach 59½.
Why does this matter for early retirees? Under the standard rules, withdrawals from pre-tax accounts count as income and can carry a 10% penalty if you are under 59½. A conversion ladder avoids that penalty on the converted principal once the five year clock has run. The cost is the tax you pay at conversion, which you influence by choosing how much to convert each year. The PenaltyFreeRetire Roth Conversion Ladder calculator gives you a simplified federal projection of how those years might line up, which is a place to start rather than a finished answer.
What Is the "Conversion Sweet Spot"?
The phrase describes the amount that fills your current tax bracket without pushing income into the next one. It is a useful frame rather than a precise answer, because the number that fits you also depends on everything else happening on your return.
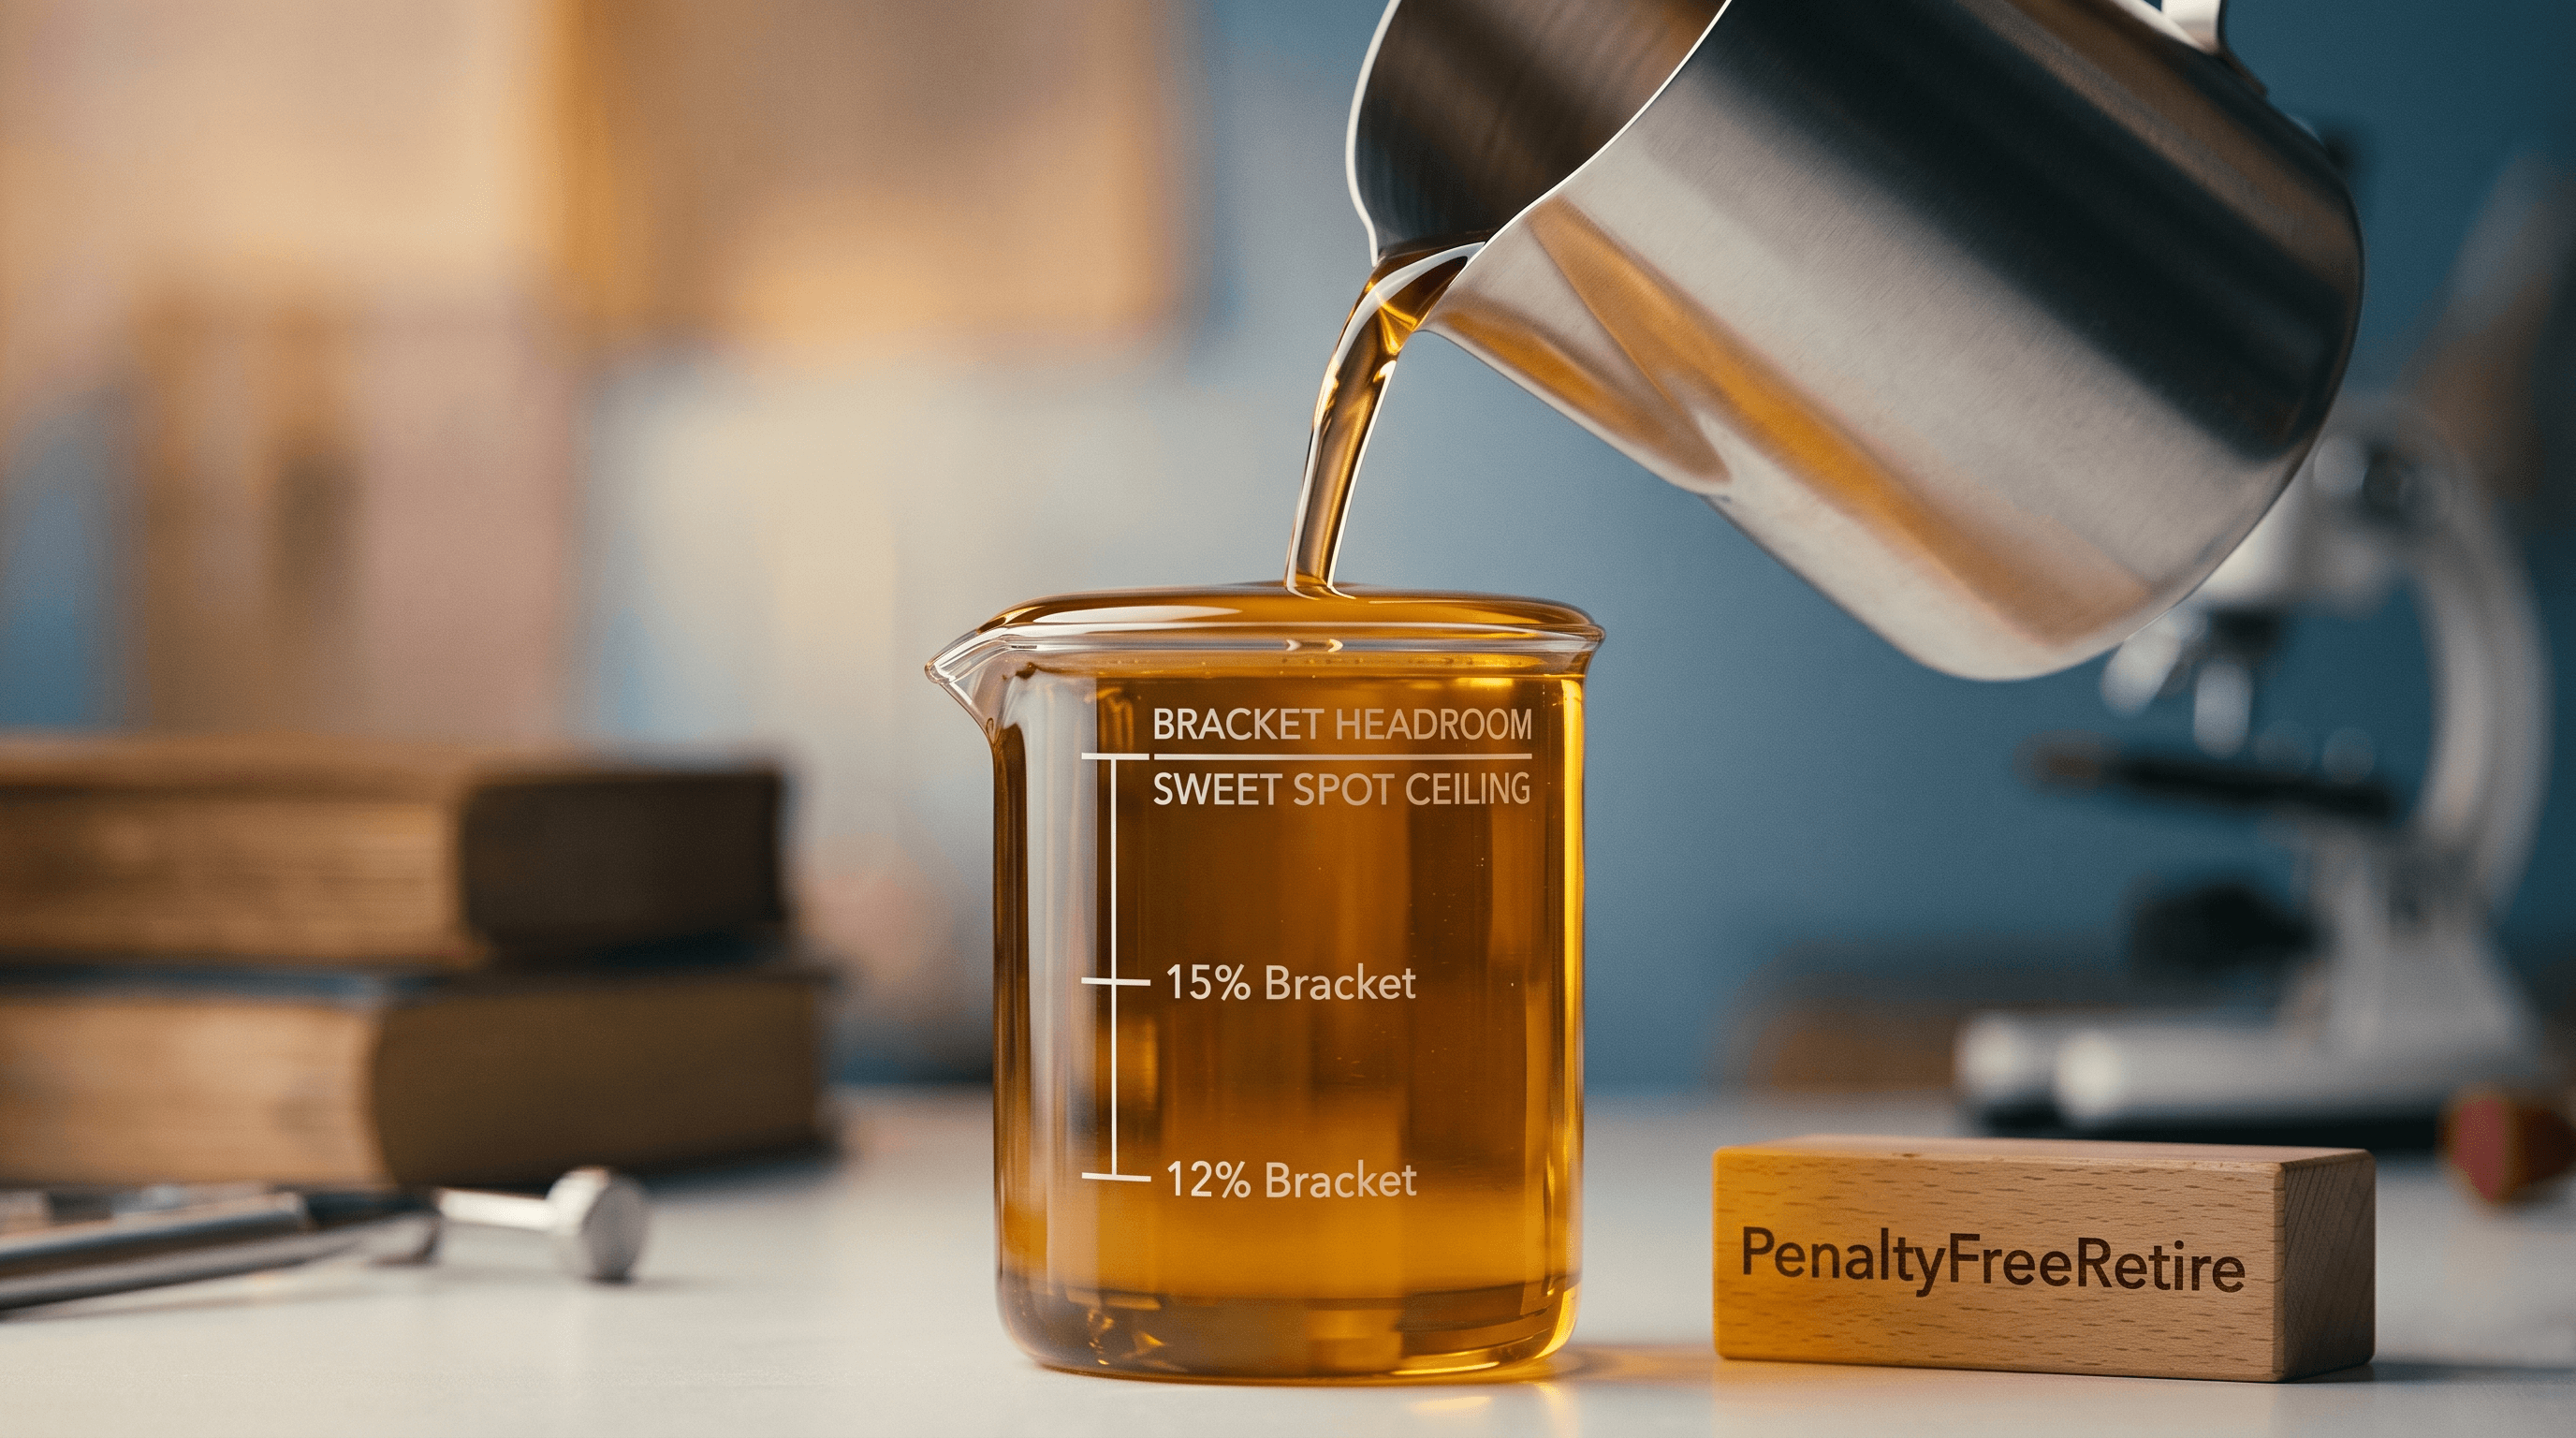
Think of your tax bracket as a bucket. Your taxable income (wages, taxable interest and dividends, rental income, and the other items that flow through your 1040 after your standard or itemized deduction) already fills part of that bucket. The space between that taxable income figure and the top of the bracket is your conversion room.
Federal brackets are progressive. Every dollar converted inside your current bracket is taxed at that bracket's rate, and only the dollars above the threshold are taxed at the next rate up. Crossing a bracket line does not re-tax the rest of your income or the rest of your conversion. It raises the rate only on the portion sitting above the line, which is often a smaller cost than people expect, though still a real one on a large conversion.
Here is a concrete example. For 2026, the 12% bracket for a single filer runs up to about $50,400 of taxable income, meaning income measured after the standard or itemized deduction rather than gross pay. If your taxable income for the year lands at $28,000, your bracket headroom is roughly $22,400. Convert $22,400 and all of it is taxed at 12%. Convert $25,000 and the first $22,400 is still taxed at 12% while only the last $2,600 is taxed at 22%. That higher rate on the spillover adds about $260 of federal tax. Repeat the pattern year after year and the difference compounds.
That is why bracket headroom is a useful planning number. The question is not how to minimize tax in a single year. It is how many dollars you are willing to move at today's rate compared with the rate you expect to pay on that same money later. If you expect higher rates in the future, filling the bracket now may be attractive. If you expect lower rates, or your income picture is about to change, converting less may serve you better.
Step-by-Step: How to Find Your Optimal Amount
You can sketch this out yourself with your most recent tax return and the current federal brackets. Treat whatever you come up with as an estimate and check it against your own numbers before you move money.
- Look up your marginal tax bracket. Check the federal brackets for your filing status. Are you at 12%? 22%? Somewhere else?
- Find the bracket ceiling. Each bracket has a top, and that top is stated in taxable income. For single filers in 2026, the 12% bracket ends around $50,400 of taxable income. For married couples filing jointly, it ends around $100,800. Both figures apply after the standard or itemized deduction and the other items on your return, so they sit higher than they look next to a gross salary.
- Subtract your other taxable income. Line 15 of your 1040, taxable income, is the starting point. If you expect changes such as a side gig, the sale of a rental property, or income from a conversion you already made, adjust for them.
- The remainder is your conversion room. That figure is how much you could convert while staying inside your current bracket. Whether it makes sense to convert all of it, part of it, or none of it depends on the rest of your tax picture.
- Repeat every year. Brackets are adjusted for inflation. Your income changes. Your deductions change. What looked reasonable last year may not fit this year.
The PenaltyFreeRetire Roth Conversion Ladder calculator follows this general approach. You enter your filing status, your taxable income, and the bracket you are aiming at, and it estimates your headroom and the federal tax on amounts above it. It is a simplified federal projection. It does not model every line of a tax return, state income tax, ACA premium tax credits, Medicare IRMAA surcharges, or changes in the law after the year you run it. Use it to frame the question, then confirm the details against your own return or with a tax professional.
Common Mistakes to Avoid
- Converting too much in one year. Enthusiasm for tax-free growth leads some people to move large amounts at once. A single large conversion can compress what might have been several years of bracket filling into one year, taxing part of it at a higher rate. Spreading conversions out is the reason the ladder exists.
- Rolling over the wrong 401(k). The Rule of 55 applies to a distribution from the plan of the employer you separated from during or after the calendar year you turn 55, and only if that plan's own terms allow such withdrawals. Each employer's plan is evaluated separately, so balances left behind at prior employers do not count (qualified public safety employees and private-sector firefighters may qualify at the earlier of age 50 or 25 years of service where applicable). Rolling that particular 401(k) into an IRA gives up that access, so if you are counting on it as a bridge, think carefully before combining accounts.
- Ignoring state taxes. Federal brackets get the attention, but some states tax Roth conversions as ordinary income. California is one of them. Others, such as Texas, Florida, and Washington, do not tax ordinary income at all. Check your own state's rules, because the calculator projects federal tax only.
If you are weighing whether to convert at all versus making new contributions, our post on Roth conversion vs. Roth contribution runs the comparison.
Run the Numbers for Your Situation
Theory is clean. Your situation is specific. Getting close to a number that fits means working through your actual income, your actual deductions, and your actual bracket, and then deciding what you believe about future tax rates.
The PenaltyFreeRetire Roth Conversion Ladder calculator can give you a simplified federal estimate of your bracket headroom to work from.
Open Calculator: /calculators/roth-conversion-ladder
The information provided on PenaltyFreeRetire is for general educational and informational purposes only. Nothing on this site constitutes financial, tax, legal, or investment advice. Always consult a qualified and licensed professional before making retirement or tax decisions.
Frequently Asked Questions
What is the Roth Conversion Ladder?
It is a strategy used by some early retirees. You convert money from a Traditional IRA or 401(k) to a Roth IRA, pay tax on it now, wait five years, then withdraw the converted principal without the early withdrawal penalty.
How much can I convert each year?
There is no IRS cap on how much you can convert. The practical limit most people work with is bracket headroom, the gap between your taxable income and the top of your current bracket. You can convert past that point, but the dollars above the line are taxed at the next rate up.
Does a Roth conversion count as income?
Yes. The amount you convert is treated as ordinary income in the year of conversion. That is why a large conversion can push part of your income into a higher bracket, where only the portion above the threshold is taxed at the higher rate.
Can I undo a Roth conversion?
No. Recharacterizing a Roth conversion was eliminated by the 2017 Tax Cuts and Jobs Act. Once you convert, the decision is final.
What happens if I convert too much?
The dollars that sit above the bracket threshold are taxed at the next rate up. Only that portion is affected, not the whole conversion and not the rest of your income. Because the conversion cannot be reversed, the extra tax stands for that year.
How long do I have to wait to withdraw?
Five years from January 1 of the year you made the conversion. Convert in 2026 and that converted principal is generally reachable without the early withdrawal penalty starting January 1, 2031. Each conversion starts its own five year clock, and earnings follow separate rules tied to age 59½.
Do state taxes apply to Roth conversions?
It depends on your state. Some tax conversions as ordinary income. Others have no income tax at all. Check your state's rules or ask a local tax preparer.
Should I convert all at once or spread it out?
It depends on your situation. Converting everything in one year usually means paying a higher rate on part of the money, so spreading conversions across several years is the more common approach. Someone who expects much higher rates later, or who has a single unusually low income year, might reasonably decide otherwise.
Sources
Disclaimer: The information on PenaltyFreeRetire is for general educational and informational purposes only. Nothing on this site constitutes financial, tax, legal, or investment advice. Tax laws change and individual circumstances vary. Consult a qualified CPA or fee-only financial planner before implementing any early withdrawal strategy. IRS Publication 575, Publication 590-B, Internal Revenue Code Section 408A and IRS Notice 2022-6 contain the authoritative rules.
Official sources used for this article
Free email guide
Want the one-page Roth conversion version?
Get the cheat sheet by email. It covers bracket room, the 5-year wait, and the mistakes that tend to cost the most.
- How to estimate your bracket room before you convert
- What the 5-year rule actually means in practice
- The mistakes that quietly add tax, penalties, or bad timing
We store your email and optional first name in Supabase to send the guide and record your choices. Resend delivers the email. If you do not opt into updates, we delete the record 90 days after your most recent guide request. See our Privacy Policy. Educational only. Not tax or investment advice.
Try the calculator
Put this strategy into numbers with our free Roth calculator.
Open Roth Calculator →Related Articles
Can You Still Afford to Retire Before 65 in 2027?
Yes, retiring before 65 can still work in 2027. But you cannot have the health insurance part of the plan be a rough monthly guess. You need a local premium quote, an estimate of your 2027 Marketplace income, and enough room for deductibles and other costs before Medicare begins.
Should You Delay Social Security to Create More Roth Conversion Room?
Sometimes yes. Delaying Social Security can give you cleaner low-income years to move money from a traditional IRA to a Roth IRA. But that only helps if you already have a workable bridge for spending.
Can a Roth Conversion Raise Your ACA Premiums? How to Plan the Subsidy Tradeoff Before Medicare
Yes. A Roth conversion can raise your health insurance cost before Medicare. The reason is simple: the taxable part of the conversion increases your income for the year, and Marketplace savings are based on household income. That means the next conversion dollar can do two things...
What Are Required Minimum Distributions — and How to Delay or Reduce Them
Required minimum distributions generally begin at 73 for people born in 1951 through 1959 and at 75 for people born in 1960 or later. Here is how RMDs work, why they can raise taxes and Medicare costs, and what you can still do before they start.